The short answer
Pick last month. Download a statement for every card and account the family used, write down cash spending, and put all of it in one list. Take out money that only moved between your own cards. What remains is what the month cost. Then sort it into needs, wants and savings, and compare the shares with a 50/30/20 split.
A family budget built on a guess tends to fail at month end. One built on last month's real numbers starts from what you already do.
Collect every card for the same month
Say the salary lands on one bank's card, daily shopping goes through Birbank, online payments through Leobank, and a Revolut card covers travel. Each bank app shows only its own cards, so no single app has the month.
- Choose one calendar month and use the same dates for every account.
- Download a statement for each card and account: the salary card, the everyday cards, any card a partner or parent uses for the household. The Birbank walkthrough shows where Birbank keeps its statement; for other banks, look under the card's history or statements in the app, or ask the bank.
- Add cash. Write down the larger cash payments you remember, such as the bazaar, a tutor or a repair. Small change can go in one line.
Leave out what is not spending
- Transfers between your own cards. Moving 300 AZN from the salary card to Birbank is not spending. Only what Birbank then pays for is.
- Cash withdrawals. Count what the cash paid for, not the withdrawal itself.
- Refunds. Subtract a refund from the purchase it reverses.
Keep loan and installment payments in the list, as their own line. They leave every month, so they belong in the total.
Sort into needs, wants and savings
The 50/30/20 rule is a rough guide: 50% of income for needs, 30% for wants and 20% for savings.
- Needs: rent or mortgage, utilities, groceries, transport, phone and internet, medicine, school, loan payments.
- Wants: eating out, delivery, clothes beyond the basics, subscriptions, entertainment, travel.
- Savings: what was put aside or paid off early.
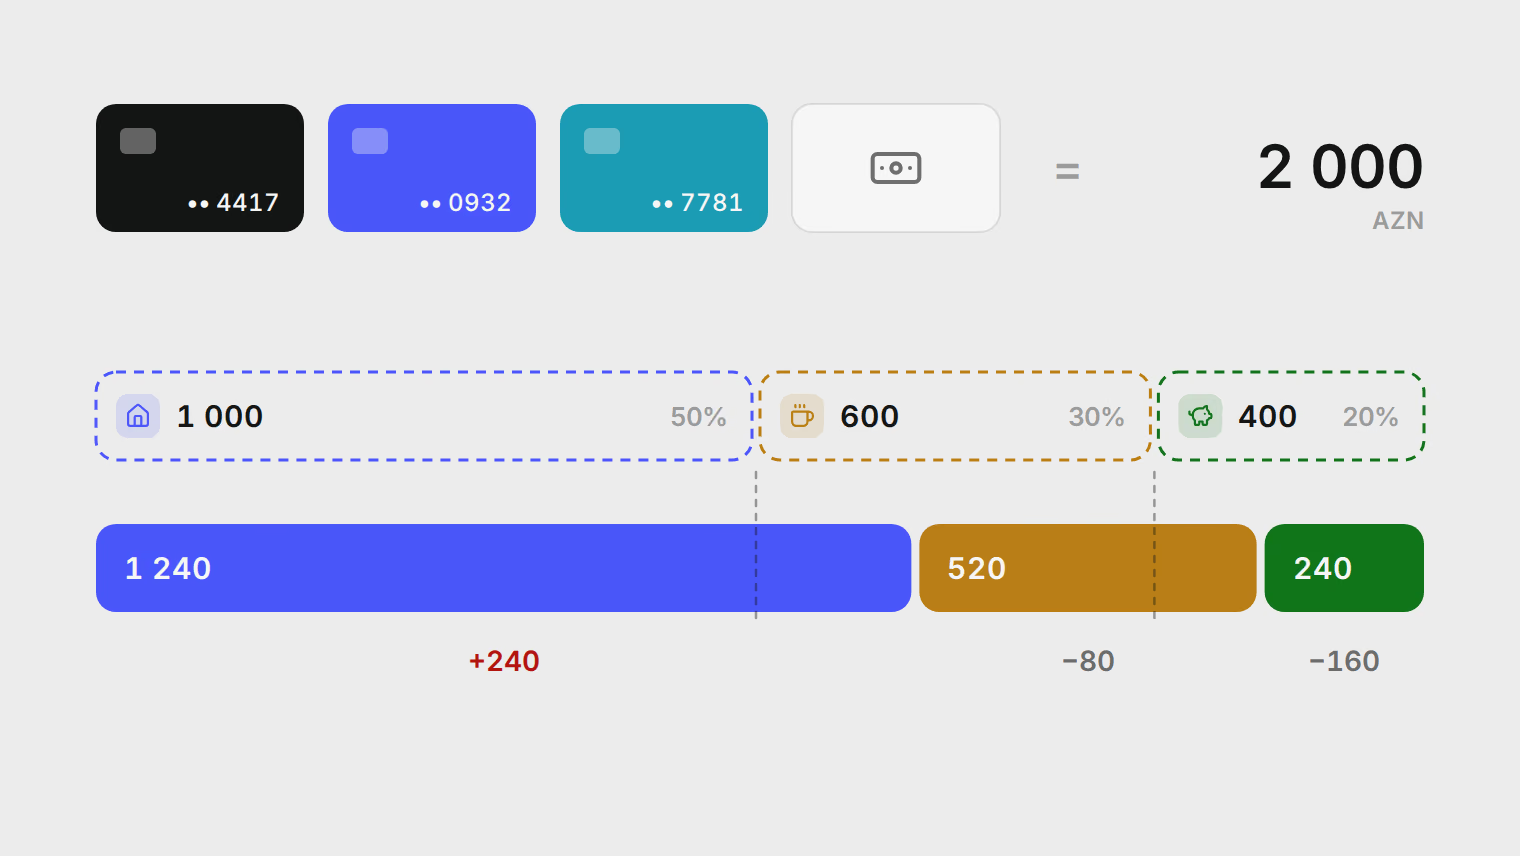
Here is a split for an example household with 2,000 AZN of monthly income. The figures are illustrative, not an average.
| Share | Target | Example month | Difference |
|---|---|---|---|
| Needs (50%) | 1,000 AZN | 1,240 AZN | +240 AZN |
| Wants (30%) | 600 AZN | 520 AZN | -80 AZN |
| Savings (20%) | 400 AZN | 240 AZN | -160 AZN |
Here needs run over while wants are already under target, so cutting eating out will not close the gap. The useful questions are about the needs line: the rent, the loan, the transport.
If needs already take 70% of income, the problem is not the cinema.
Repeat it each month
The first month takes the longest. After that, a routine on payday is enough: download last month's statements, check what changed, and look at anything new that repeats. A new subscription or a price rise shows up as a charge you did not see last month; finding recurring charges covers how to spot them.
How Pulget does the counting
Pulget reads the statements, so you do not retype them. It does not connect to any bank; everything comes from the files you upload.
- Create one account in Pulget for each card or bank account, in its currency, and upload its statement: PDF, CSV, XLS, XLSX or DOCX. Scanned PDFs are read with OCR.
- Check the extracted dates, amounts, merchants and categories, then approve them. Merchant names are matched against 887 known brands, including Azerbaijani ones such as Bravo, Araz Market, OBA, Bazarstore, Azercell and Bakcell.
- Choose manat as your reporting currency when you set up Pulget. A Revolut card in euros or a deposit in dollars is converted at the published rate for each transaction's date (or the closest earlier one), and the original amount is kept. Manat rates come from the Central Bank of Azerbaijan when the main rate source has none. The multi-currency guide explains the conversion.
- A transfer between two of your accounts in the same currency, for the same amount, can be suggested as a pair in the Review inbox. Accept the pair and it counts as a transfer, not as spending. Group other transfers yourself on the Transactions page.
- Confirm the recurring bills Pulget suggests for charges that repeat on a steady schedule. Add cash payments by hand to a cash account in the same reports.
Insights then shows income, spending and net cash flow by month, and spending by category, across all the cards.
What Pulget will not do
It has no budgets or spending limits: it shows what was spent, and the 50/30/20 comparison is yours to make. It shows no live balance and knows only what you upload. During preview every workspace is on Standard, which counts up to 3 accounts; pricing lists the file limits. Parts of the app are still in English while the rest is translated.
Start with one month
Upload last month's statement from the card you use most, free during preview, and check the result before adding the other cards. Tracking spending without a bank connection explains the review step.
Related reading
About the author
Hikmat Samadov, Founder. Hikmat builds Pulget, a spending tracker that reads the bank statements you upload instead of connecting to your bank.